

Understand how Class 1A National Insurance (NI) is calculated, reported, and displayed in UK Payroll when processing termination payments.
When an employee receives a termination payment, Class 1A NI is charged at 15% on the taxable amount above £30,000. This rule has applied since April 2020.
If you use the termination award pay item for redundancy or ex-gratia payments that exceed £30,000, UK Payroll automatically calculates the Class 1A NI for you—no manual setup or adjustment is required.
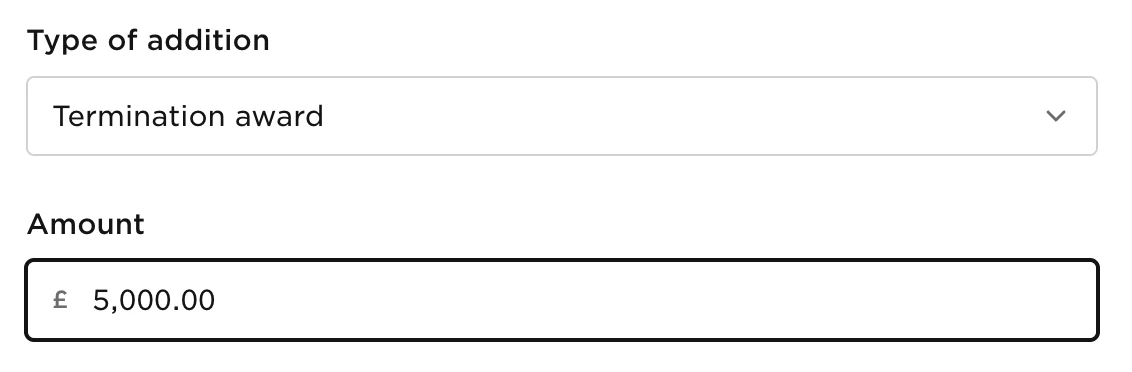
For step-by-step guidance on setting up and processing termination awards (including PILON), see:
Process termination pay and PILON
Class 1A NI on termination payments is treated as an off-payroll liability. Because of this, it doesn’t appear as a separate column in standard payroll reports.
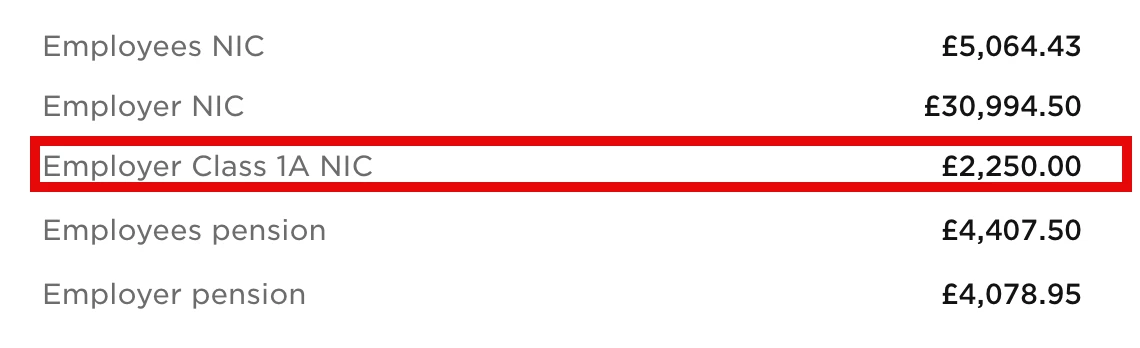
You’ll see Employer Class 1A NIC listed in the payroll summary. For HMRC reporting purposes, the liability is transmitted automatically in your FPS submission on payday.
The total Class 1A due will appear:
-
On your payroll summary screen
-
On your P32 report
If you have a PAYE Settlement Agreement (PSA), note that this does not cover Class 1A NI on termination payments. PSAs apply only to Benefits in Kind. Class 1A NI on termination awards is a separate liability and does not require P11D filing.
Once calculated, the Class 1A NI is included in your FPS submission and sent to HMRC automatically.