

As the new tax year begins in April, employers must navigate a range of changes and requirements when processing the first payroll. One of the key aspects for businesses with directors is ensuring that payroll, National Insurance Contributions (NICs), and directorship methods are aligned with current tax laws. For directors, the first payroll run of the year is crucial for compliance and maintaining accurate records.
Changing the National Insurance Method for a Director in April
April provides employers with an opportunity to reconsider and adjust the National Insurance (NI) method applied to directors. This flexibility is particularly important, as directors are subject to different rules for calculating NI contributions compared to regular employees.
Directors, unlike standard employees, are subject to annualised earnings periods for NIC purposes. This means that rather than calculating NICs on a weekly or monthly basis, the director’s earnings are considered for the full tax year to determine the applicable NICs. However, if employees feel that this method doesn’t suit their financial situation, the April payroll run offers the opportunity to change how NICs are calculated for directors.
Options for Changing the NI Method
Annual Earnings Period Method (Standard Method):
This is the standard method for directors. Their NI contributions are calculated on an annualised basis, which means the director’s total salary for the year is divided by the number of pay periods, typically 12 if paid monthly, treating earnings on a cumulative basis.
The advantage of this method is that it accounts for fluctuations in income throughout the year and ensures that NICs are paid evenly.
Reverting to Monthly or Weekly Method (Alternative Method):
Employers can choose to treat the director’s earnings as they would for any other employee and calculate NICs on a monthly or weekly basis instead of the annualised method.
With this method a recalculation is completed at the end of Month 12 to reconcile the cumulative, year-end NIC liability with the monthly contributions already made.
This approach may be suitable if the director receives a relatively consistent monthly salary and the annualised method is proving to be more complex or administratively burdensome.
If you decide to action a change for directors and change the NI method in April, this can be done in the software by following these steps:
-
From the left side bar, select Employees.
-
Select the relevant employee.
-
On the right side, click Set as director.
-
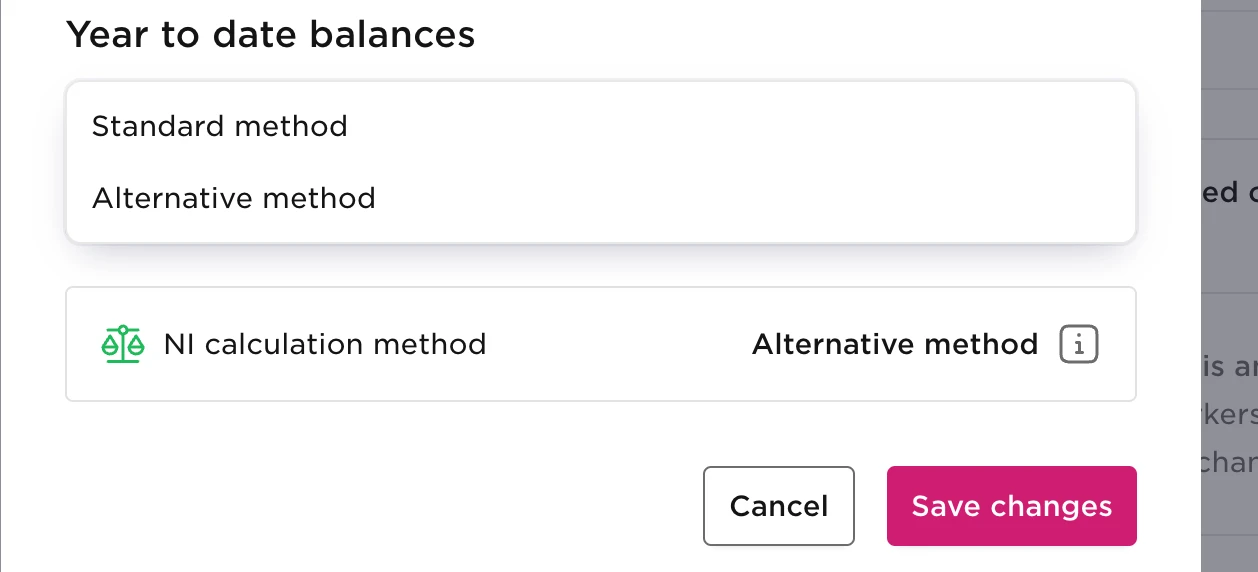
Enter the start date of directorship and select the National Insurance calculation method from the dropdown menu.
-
Click Set as director.
-
If the employee is already a director and you want to make a change, you can press the Edit option to change the NI method or select End to end the Directorship.
-
Once in the next window, this will then allow you to change the NI method which will then reflect on the rest of the tax year.
It is important to note that when you action these changes, please review the NIC contributions in the first run to ensure that everything is correct and accurate to what method has been chosen.